Designing the basic benefits of a long-term care insurance plan, whether it is a traditional standalone policy or a hybrid life/LTC plan, is relatively straightforward: Choose an initial monthly benefit. Decide whether you want that benefit to grow over time through inflation protection. Then determine whether having a death benefit or cash value is important if long-term care is never needed.
8 min read
A Convenient Way to Use Qualified Retirement Assets to Fund Long-Term Care Insurance
Topics: Long-Term Care Retirement Planning Limited & Extended Care Planning Center Knowledge Centers
4 min read
“My Family Will Take Care of Me.” Have We Asked the Family?
When discussing extended care planning, agents often hear a familiar response: “I don't need long-term care insurance. My family will take care of me.”
For many clients, that statement comes from a good place. They have close relationships with their spouse, children, or other family members and believe those people will be there when they need them. And they may be right. But there is an important follow-up question: Have we asked the family?
There is a significant difference between a family member being willing to help and being prepared to become a caregiver. Extended care planning isn't about questioning whether someone's family loves them enough to provide care. It's about making sure that love doesn't become the family's only plan.
Topics: Long-Term Care Limited & Extended Care Planning Center Knowledge Centers
5 min read
The Retirement Conversation Most Advisors Aren't Having (But Should Be)
For decades, retirement planning has centered around a familiar set of questions:
- How much have you saved?
- Will your portfolio generate enough income?
- What rate of return do you need?
- When should you claim Social Security?
These are important questions. But there's another one that often gets overlooked:
What happens if retirement lasts longer, costs more, and includes a long-term care event?
Topics: Long-Term Care Retirement Planning Financial Planning Health Care Limited & Extended Care Planning Center Knowledge Centers Lifetime Healthcare Center
8 min read
Think Traditional and Linked LTC Insurance are World's Apart? Think Again.
Recently an advisor brought to us an opportunity to help someone plan for long-term care. Like many purchasers, this was someone who had personal experience - a 50 year old single man who was overseeing the care of his Mom with Alzheimer's. He is self-employed, lives in Illinois and has an annual income of about $150,000. We presented the advisor with two options for their client - a traditional policy and a linked-benefit life/LTC plan.
Topics: Long-Term Care Long-Term Care Insurance Limited & Extended Care Planning Center Knowledge Centers
3 min read
When One Spouse Qualifies and the Other Doesn't: Navigating Long-Term Care Planning Together
One of the most difficult conversations I have with agents and clients isn't when a policy is approved; it's when one spouse qualifies for coverage and the other does not. This scenario is more common than many people realize. Couples often assume they will either both qualify or both be declined. Unfortunately, underwriting doesn't work that way. Every applicant is evaluated individually based on their own health history, medications, cognitive status, medical records, and overall risk.
Receiving mixed underwriting decisions can be disappointing and, at times, overwhelming. I've heard spouses ask, "How can one of us be approved and the other declined? We have lived the same life." The answer is simple: our bodies don't always age the same way.
Topics: Long-Term Care Long-Term Care Insurance Limited & Extended Care Planning Center Knowledge Centers
5 min read
The LTC Conversation Went Well…Now What?
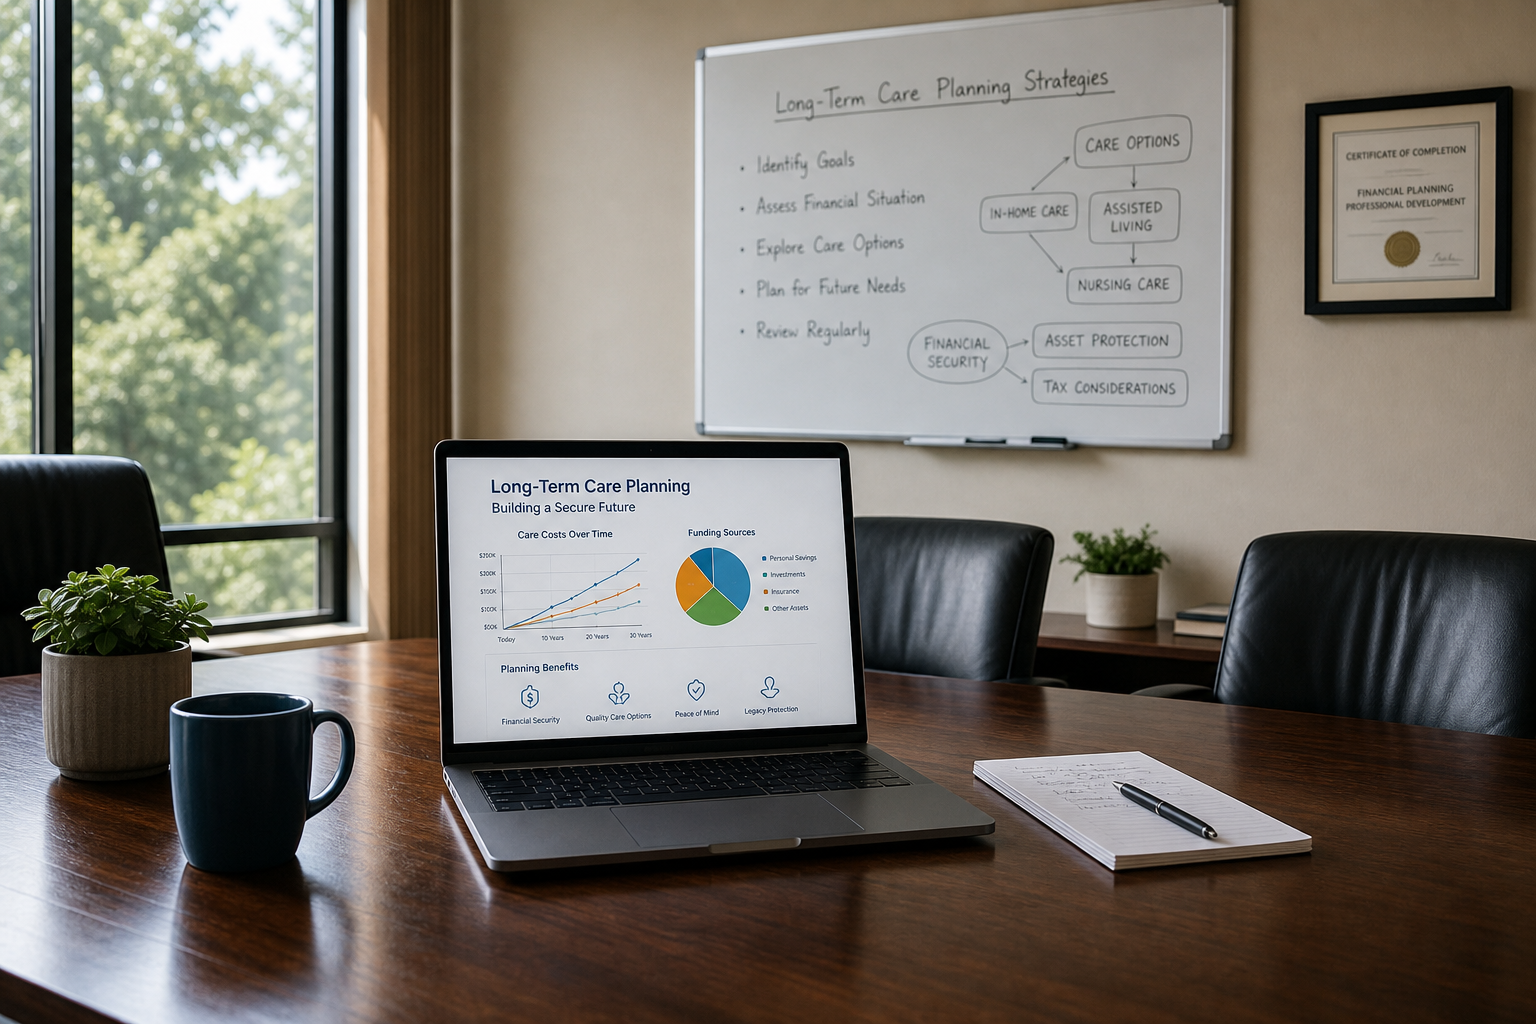
You’ve discussed the cost of care. You’ve explained that Medicare generally doesn’t cover ongoing custodial long-term care. You’ve reviewed the potential impact on retirement assets and family members. Your client agrees that extended care planning makes sense.
And then…nothing happens.
For many advisors, one of the most challenging parts of extended care planning isn’t starting the conversation—it’s helping the client decide and move forward. The key is recognizing that clients aren’t simply buying insurance. They’re making decisions about aging, independence, finances, and family. That can make procrastination easy. Your role is to help turn an uncomfortable future possibility into a manageable plan.
Topics: Long-Term Care Long-Term Care Insurance Limited & Extended Care Planning Center Knowledge Centers
5 min read
Working Smarter: How AI and Technology Are Reshaping Insurance Case Management
For years, our industry has searched for the perfect balance between efficiency and service. Clients expect timely decisions, agents want proactive communication, and organizations strive to create a seamless experience from application submission to policy placement. The challenge has never been a lack of dedication. Insurance professionals have always worked tirelessly to move cases forward. The challenge has been finding ways to eliminate unnecessary delays, reduce administrative burdens, and create greater visibility throughout the process.
Today, technology and artificial intelligence are helping make that possible. The insurance industry is experiencing a significant transformation as modern tools streamline workflows, improve communication, and provide greater insight into the status of each case. While expertise, judgment, and relationships remain at the heart of what we do, technology allows professionals to focus more of their time on meaningful interactions and less on repetitive administrative tasks.
Topics: Technology Limited & Extended Care Planning Center Insurance Artificial Intelligence Knowledge Centers
4 min read
Aging in Place: The Impact of Proactive Wellness Programs on Long-Term Care Needs
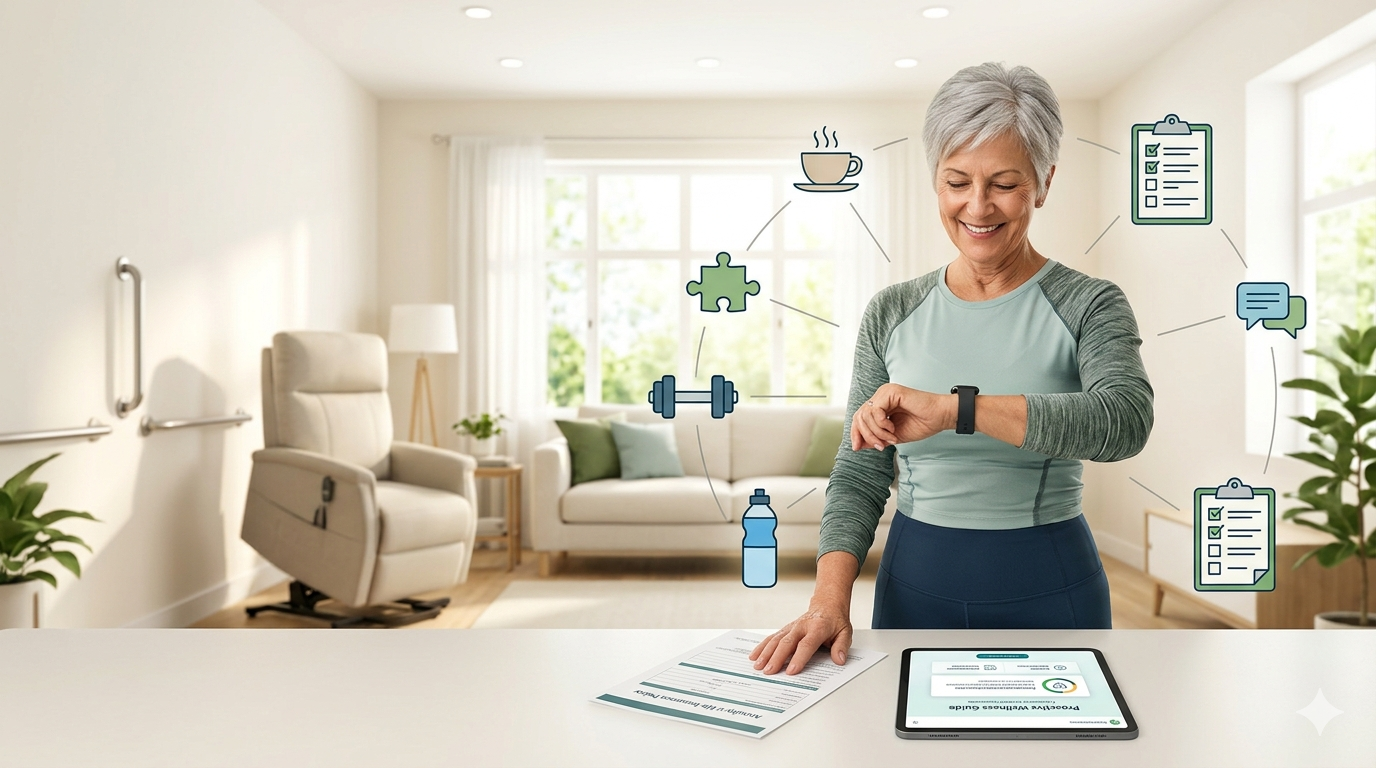
For many Americans, the goal of retirement isn’t just financial well-being, it’s the ability to remain at home, maintain their lifestyle and enjoy the independence of a secure, healthy future.
In fact, 88% of adults aged 50 to 80 say they want to age in place.1 Yet planning for the future often centers on the funding need for long-term care (LTC) services, rather than reducing the likelihood or extent of those needs from the outset.
Topics: Long-Term Care Limited & Extended Care Planning Center Knowledge Centers
4 min read
Longevity Planning: Clients Are Living Longer, But Are They Living Healthier?
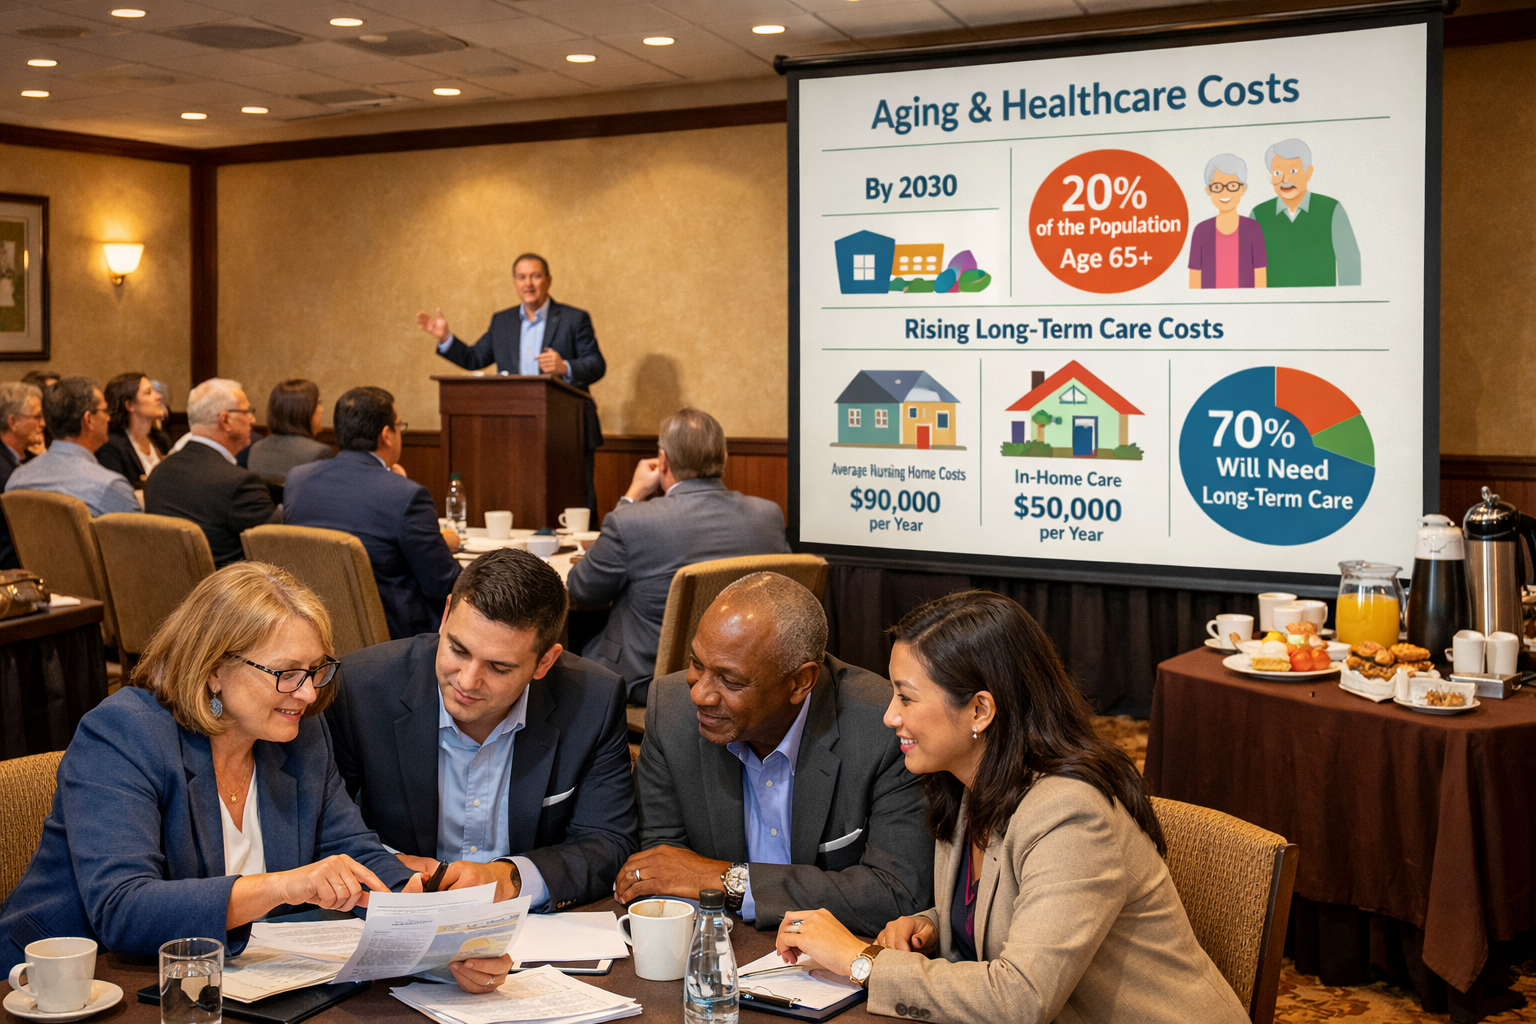
For decades, retirement planning focused on one core question: Will my clients outlive their money? Today, advisors face a more complex challenge: Will clients outlive their health? Advances in medicine, technology, and healthcare have extended life expectancy, allowing more Americans to reach their 80s and 90s than ever before. But longevity itself is not necessarily the victory clients imagine. The real issue is whether those extra years are healthy, independent, and financially sustainable.
For insurance and financial professionals, longevity planning is no longer optional. It has become one of the most important conversations agents can have with clients approaching retirement.
Topics: Long-Term Care Health Care Limited & Extended Care Planning Center
3 min read
Too Many Health Issues to Qualify for LTCI: A Common Misconception
One of the most common reasons people avoid exploring long-term care insurance (LTCI) coverage is a simple belief: “I have too many health issues, so I won’t qualify anyway.”
This assumption stops the conversation before it even begins. The reality? Underwriting is far more nuanced than most people think. Having health conditions does not automatically disqualify you. In fact, many individuals with medical histories are still approved, especially when those conditions are stable, well-managed, and properly documented.