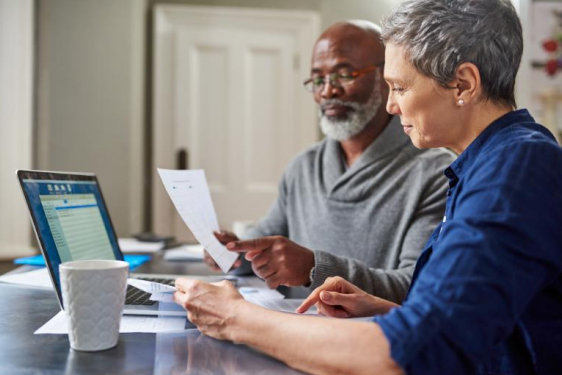
When discussing extended care planning, agents often hear a familiar response: “I don't need long-term care insurance. My family will take care of me.”
For many clients, that statement comes from a good place. They have close relationships with their spouse, children, or other family members and believe those people will be there when they need them. And they may be right. But there is an important follow-up question: Have we asked the family?
There is a significant difference between a family member being willing to help and being prepared to become a caregiver. Extended care planning isn't about questioning whether someone's family loves them enough to provide care. It's about making sure that love doesn't become the family's only plan.
What Does “Take Care of Me” Actually Mean?
When clients say their family will care for them, ask them what that looks like.
Does it mean occasionally helping with groceries and transportation? Or does it mean helping someone bathe, dress, eat, use the bathroom, manage medications, or safely move from a bed to a chair? Does it mean a few hours each week or several hours every day? Who will coordinate doctor's appointments, communicate with providers, manage medications, arrange paid caregivers, and make decisions if the client's needs change? And what happens if care continues for several years?
 |
| Mary Sizemore, CLTC, LTCCP Insurance Communications and Marketing Coordinator Krause Agency |
These questions aren't designed to frighten clients. They help turn an assumption into an actual plan.
The Family May Be Willing but Are They Able?
Adult children often say they would do anything for their parents. The problem is that they may already be raising children, working full-time, managing their own households, saving for retirement, or even caring for another family member. A spouse may also assume the role of primary caregiver, but that can become increasingly difficult as care needs become more complex.
Ask your clients this: “Who has the time, physical ability, financial resources, and flexibility to provide the care you may need?”
There's a Cost to Unpaid Care
Family caregiving may be unpaid, but it isn't free. A family member may reduce work hours, use vacation time, pass up a promotion, change jobs, or leave the workforce altogether to provide care. There can also be expenses for transportation, meals, home modifications, supplies, respite care, and other needs.
Then there is the emotional cost. Caregiving can change relationships. A spouse becomes a caregiver. A daughter becomes a care coordinator. Siblings may disagree about who should provide care, where a parent should live, or how expenses should be handled.
These consequences often aren't considered when a client casually says, “My family will take care of me.”
Ask the Question Before the Family Has to Answer It
One of the most valuable things an agent can do is encourage clients to have the conversation with their family before a care event occurs. Clients may discover that their children absolutely want to help but their idea of helping may be very different from providing hands-on care every day.
Insurance Doesn't Replace the Family
This is where agents can reposition the role of long-term care insurance. Coverage isn't necessarily about replacing family caregivers. It can be about giving the family resources and choices.
Benefits may help pay for professional home care so an adult child can remain a daughter or son instead of becoming a full-time caregiver. They may help a spouse bring in additional assistance. They may provide more choices if assisted living or another care setting eventually becomes appropriate. Even a policy that doesn't cover every dollar of care can help reduce the amount of care the family must personally provide or pay for.
‘My family will handle it” isn't a complete extended care plan until the family understands the expectation and has the resources to carry it out. As an agent, you don't have to tell clients how they should receive care. Your job is to help them think through the possibilities before a crisis makes those decisions for them.
The Bottom Line
Most families want to be there for one another. But there is a difference between being there and being responsible for providing all of someone's care. A good extended care plan doesn't remove the family from the picture. Rather, it may help protect their ability to remain family.
So, the next time a client tells you: “My family will take care of me.” Ask one more question: “Have you asked them?”